Monetary policy rate sits with limited head rooms to interplay with, as it can’t be reduced anymore now!

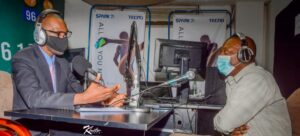
Kelvin Chisanga Pastor CK with Caesar Edward Sindele at Pan African Radio
By Kelvin Chisanga, Zambian Social Economist +260 97 9305194
ZAMBIA’S apex bank (Bank of Zambia) monetary policy committee (MPC) will be sitting next week starting from Monday to Tuesday in order to make some determinations of the pricing structure on financial services and related solutions, by working out on the next set of monetary policy tone for the quarter, which shall be announced on Wednesday the 23rd November 2022.
Nevertheless, given the current situation on the ground with considerable factors, and also considering many other dynamics at play, on the prevailing patterns of growth that we have so far recorded on the economic front, it is inevitable that we are likely to see the policy rate being maintained with some few considerations in possible view but it is mostly going to be hiked in order to help counterbalance the effects seen from the global market patterns, and with aims to contrast it with a stimulus budget that we have framed up for the fiscal year 2023.
With the current performances seen in the overall domestic economy, and with the relatively stable upbeats and uptakes seen in our fiat currency (Kwacha), it’s unfortunately that private sector has not performed pretty well this year on average especially during the second quarter of the year due to some continued liquidity squeeze, where it is witnessed that the government expenditure column was a bit tight and the central bank (BOZ) on the other side, has been controlling of the money supply and its quantity in the local market, and this has also been working out tightly on the exchange rates of money exclusively to control possible spikes of inflation, since we are very much aware that the biggest factor of inflation comes out from this particular economic portion, and it’s the whole essence that keeps interplaying into the monetary policy in almost every nation that drive importation on high scale, so with this intervention in place, it comes in, very handy with the case of fostering price stability.
In the Zambian situation, we normally use two key fundamental factors of determining monetary policy stance, and thus the expansionary monetary policies, where they do design this policy model mainly to fight the high levels of unemployment as a strong focus, which in our current scenario, if we were to take it up this way, is also accompanying paying off debt portfolio, as it also bears with the consequence in seeing inflation sky-rotting to the roof since production might not favour with this model, luckily the inflation in the Zambian case has been decelerating from being digital (double-digits) to where we are now at single digits, and going forward we are also avoiding to break loose of it outside the single margin to allow cooling demands with the overall pricing aggregate in goods and services.
While, on the other hand, we can also use contractionary policies which are basically aimed at directly fighting inflation, but sadly with this model of policy guideline, the consequence is very much bearable in the huge number of unemployment since credit restricts production within business and investment, meanwhile it is well known fact to say that Zambia today stands at almost having 8 million unemployed populations, which is now seen as a bad effect to the projected or anticipated economic growth patterns, thus standing contrary to proposed medium-to-long term policy benchmark as suggested in the strategic framework of 8th National Development Plan and Vision 2030.
However, it is well cognizant to state that given the current prevailing circumstances with 2022 national budget and with the next year’s budget set in prospective plans, we are more likely to continue operating with the contractionary monetary policy rate, especially given the existing situation where we have seen that the budget has maintained an expansionary function. So, Zambia’s monetary policy rate is to remain this path, so that it rests on the contrary patterns as set with the fiscal stance of the central government, but both work in tandem with the IMF’s policy prescriptions of maintaining good fiscal balance in check, so from all these angles the MPR will still take through on the contractionary side, as we can’t run both on positive affirmative, with the similar policy reactions in order to help in balancing up the domestic economy.
In short, the monetary policy rate has very limited rooms to maneuver through, given the expansionary budget fixed for the financial year of 2023, and its either maintaining the current policy benchmark level or surging up a bit by a small fraction of basis percentage point of less 50% average and slightly below. With this, in forward-looking opinionated view, we will try to avoid triggering high chances of inflation, as it enables us to firmly anchor and stiffly maintain on its expectations just within and around the target range of between 6-8% target range being our desired policy corridor.
The economy will still linger with some spots of depressions emanating from a deep impact that we have experienced so far, of the debt situation, as this will potentially last us into some few more years to come, and the debt question still remains a big risk factor on our economic development and growth patterns, coupled with the immediate COVID 19 impact that has been driving an escalated effect of inflation into a global recession, and not forgetting the Russian-Ukraine crisis, so all these complex of conditions that have equally led to downscaling of the economic projections by many stakeholders which includes the IMF, world Bank etc.