Clarification on external confirmations and the appointment of Grant Thornton to audit the Road Development Agency
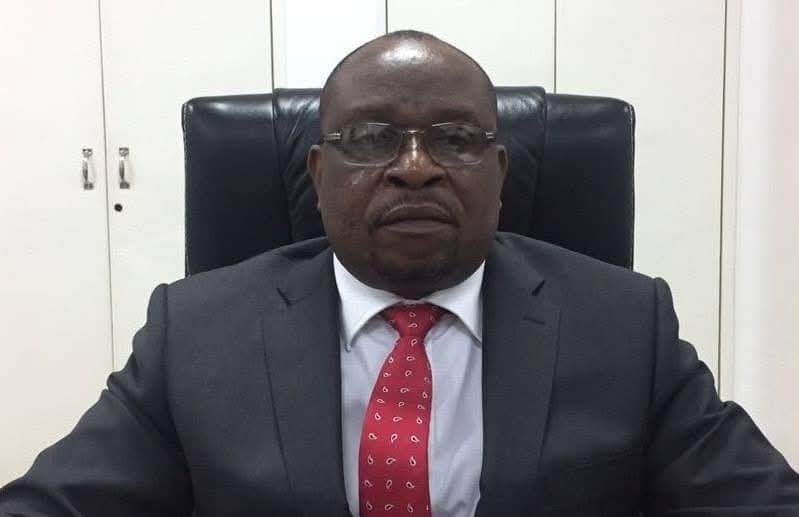
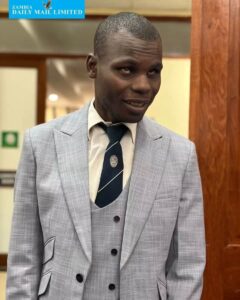
Dr. Ron M. Mwambwa, Zambia's Acting Auditor General (AAG)
10th March, 2026
To the News Editor
PRESS STATEMENT
For Immediate Release
SUBJECT: CLARIFICATION ON EXTERNAL CONFIRMATIONS AND THE APPOINTMENT OF GRANT THORNTON TO AUDIT THE ROAD DEVELOPMENT AGENCY
Following a social media post by Mr. Emmanuel Mwamba concerning the confirmation of account balances and the engagement of Grant Thornton, a private audit firm, to audit the financial statements of the Road Development Agency (RDA), the Office of the Auditor General wishes to provide the following clarification.
Confirmation of Account Balances
The Office wishes to clarify that obtaining confirmations for bank balances or creditor amounts is a standard and widely accepted audit procedure. This is in accordance with the International Standard on Auditing (ISA) 505 – External Confirmations, where auditors are required, as part of their audit procedures, to obtain external confirmations as a form of audit evidence.
External confirmation refers to audit evidence obtained as a direct written response to the auditor from a third party (the confirming party), either in paper form, electronically, or through other communication mediums. These procedures are frequently performed to confirm account balances and their elements. They may also be used to confirm the terms of agreements, contracts, or transactions between an entity and other parties, or to verify the absence of certain conditions, such as side agreements.
In practice, the public may wish to know that confirmations may be initiated in two ways. Either the auditee may request a creditor or relevant party to confirm directly to the auditors the amounts owed, or the auditor may write directly to the creditor to confirm the amount owed to them, with authorisation from management encouraging the confirming party to respond directly to the auditor. In the instance under discussion, the former approach was utilised.
The purpose of such confirmations is to ensure that amounts reflected in the financial statements as being owed to creditors are accurately stated and not misstated or misrepresented. Where discrepancies arise between the creditor’s confirmation and the amounts recorded in the financial statements, such differences are investigated and reconciled.
Accordingly, this process should not be misconstrued as a request or plea to creditors to collect outstanding dues. Rather, it is a routine audit procedure conducted in line with established auditing standards to provide independent and corroborative audit evidence. This evidence assists the auditor in forming an opinion on the fairness and accuracy of the figures reported in the financial statements.
It should further be noted that during the audit of the Road Development Agency’s financial statements, similar confirmation procedures were conducted with several other creditors reflected in the Agency’s financial records.
Appointment of External Auditors
The Office also wishes to clarify the process relating to the engagement of private audit firms.
Section 74(1) of the Public Finance Management Act No. 1 of 2018 allows the Office of the Auditor General to secure the services of agents or specialist consultants to assist the Auditor
General in the execution of duties under the Act. In addition, Section 10(1) of the Public Audit Act No. 29 of 2016 provides that where the Auditor General is unable to undertake an audit as specified under the Act, the Office may subcontract a private audit firm registered with the Zambia Institute of Chartered Accountants (ZICA) to undertake such an audit.
Consequently, where the Office faces resource limitations or time constraints in undertaking audits of financial statements for statutory bodies, it may subcontract eligible private audit firms registered with ZICA. This process is conducted in line with the provisions of the Public Audit Act No. 29 of 2016, the Public Finance Management Act No. 1 of 2018, and applicable public procurement procedures.
In this regard, the appointment of Grant Thornton Management and Chartered Accountants in September 2024 to undertake the audit of the Road Development Agency’s financial statements for the period ending 31st December 2024 through to 2026 followed a transparent procurement process. The process involved competitive bidding in which four (4) other private audit firms also participated.
It should further be emphasised that in 2024, Grant Thornton was not the only private audit firm engaged by the Office. Several other private audit firms were similarly subcontracted to conduct audits of various statutory bodies on behalf of the Office of the Auditor General.
Engaging private audit firms in this manner forms part of the Office’s normal operational practice, particularly where resource or time constraints arise. As such, the appointment in question should not be regarded as unusual but rather as part of the routine execution of the Office’s statutory mandate.
Conclusion
The Office trusts that this clarification adequately addresses any misunderstandings or misrepresentations that may have arisen from the article circulating on social media.
Members of the public are encouraged to seek clarification from the Office on any audit-related matters rather than rely on or circulate unsubstantiated claims, so as to ensure that public discourse is informed by accurate and verified information.
Issued by:
Dr. Ron M. Mwambwa
ACTING AUDITOR GENERAL
Office of the Auditor General
Republic of Zambia
… Statement in full: