Africa’s Resource Rush: Opportunity or Another Cycle of Extraction?
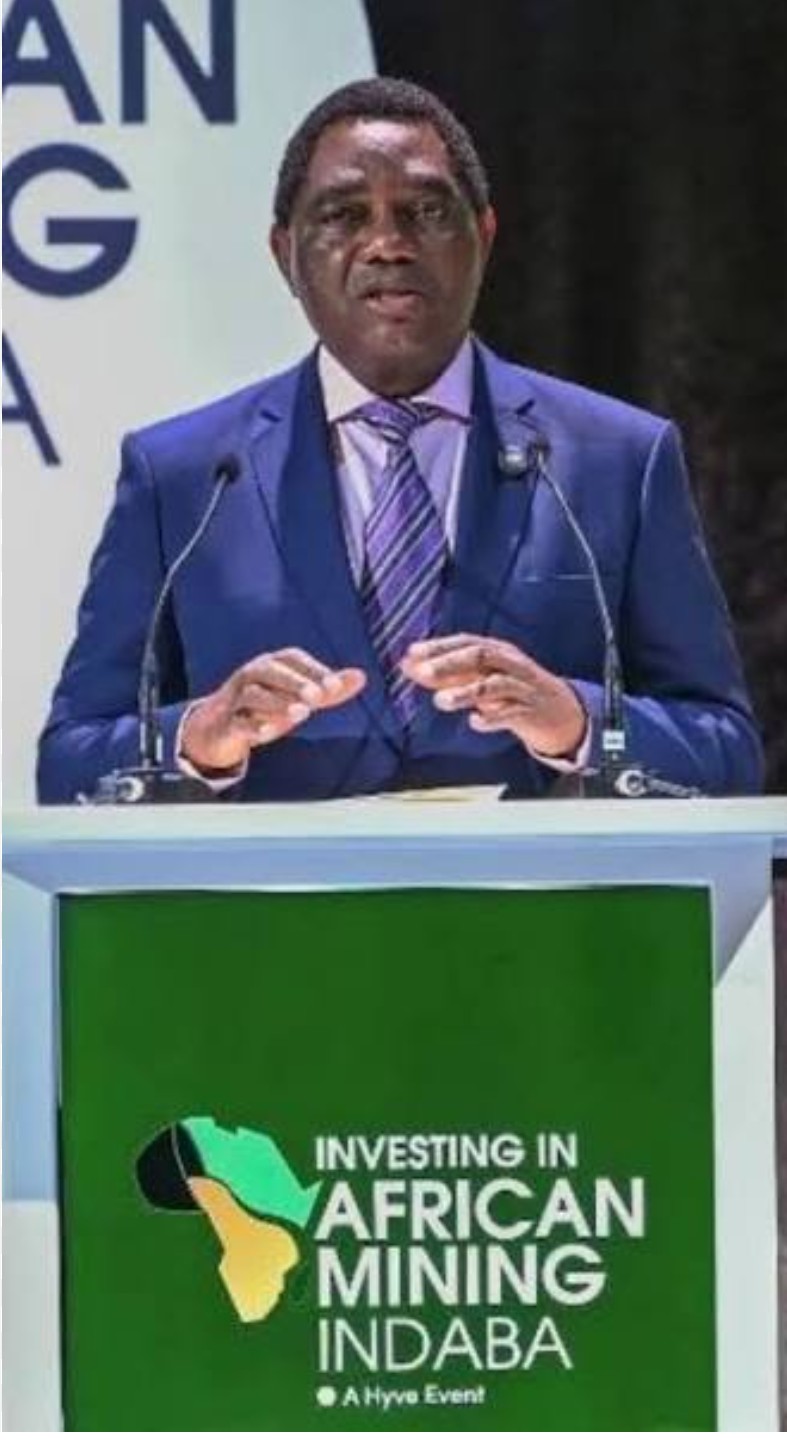
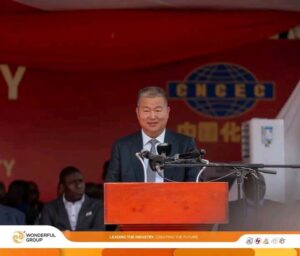
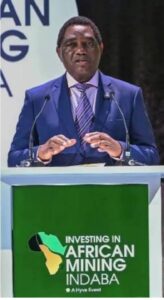
President Hakainde Sammy Hichilema at the 32nd annual Investing in African Mining Indaba ran from Monday 9th –Thursday 12th February 2026 at the Cape Town International Convention Centre
…Mining Indaba themed: “Stronger Together: Progress Through Partnerships.”
By Correspondent
Africa is once again at the centre of global competition.
This time, the scramble is not driven by colonial conquest but by the demands of the 21st-century economy — electric vehicles, renewable energy systems, digital infrastructure, and advanced manufacturing.
Beneath African soil lie the minerals and hydrocarbons that power this transition, and global powers know it.
From cobalt and copper to lithium and platinum-group metals, the continent holds some of the world’s most strategic resources.
As clean energy technologies accelerate, Africa’s geological endowment has transformed from a development talking point into a geopolitical prize.
The demand for the continent’s mineral resources was amplified at the just ended 2026 Mining Indaba held in Cape Town, South Africa.
The 32nd annual Investing in African Mining Indaba ran from 9–12 February 2026 at the Cape Town International Convention Centre under the theme:
“Stronger Together: Progress Through Partnerships.”
Attendance reached record levels, with more than 10,500 delegates, including mining executives, investors, and government officials — reflecting Africa’s rising role in global mineral supply chains.
Key event focus areas included:
Strengthening investment partnerships across public and private sectors.
Discussions on critical minerals — especially those essential for energy transition, tech, and defence.
Efforts to foster sustainable mining practices, local value retention, and community engagement.
Major Themes and Strategic Conversations included Mining Partnerships and Supply Chain Security.
A major thread was how Africa can work with global partners to build robust, value-adding mineral economies — from extraction through processing and manufacturing — rather than remain exporters of raw ore.
Critical Minerals and the Energy Transition was another area the Mining Indaba looked at.
Africa’s strategic importance lies in its vast stores of cobalt, copper, lithium, manganese, platinum group metals, and rare earths — all crucial for renewable energy, batteries, and advanced technologies.
This broader narrative set the stage for heightened geopolitical engagement by both the U.S. and China.
U.S. Interest and Strategic Engagement
Shift Toward Investment Diplomacy
The United States is actively reorienting its approach from traditional diplomacy to investment and supply-chain partnerships aimed at securing access to critical minerals.
Rather than only mining operations, U.S. interests are focusing on:
Offtake agreements (pre-purchase contracts).
Price guarantees and financial incentives.
Partnering with African governments and private firms.
Strategic Positioning
U.S. participation at Mining Indaba emphasized:
Reducing dependency on China-controlled supply routes for cobalt, copper, and other minerals.
Leveraging capital markets, technology, and governance standards as competitive strengths.
Diplomatic Frictions
A notable moment at the Indaba was the public clash regarding the Democratic Republic of Congo’s (DRC) critical minerals deal with the U.S. — where South Africa’s Mines Minister challenged the DRC’s framework agreement, signaling broader continental sensitivity around great-power influence.
The DRC indicated it would explore other partnerships if the U.S. framework did not yield concrete projects or fair value.
China’s Continued Footprint and Competitive Edge
Enduring Presence in Mining Investment
China remains deeply entrenched in African mining, particularly in copper, cobalt, and other key minerals — continuing long-term investments and infrastructure ties.
This includes large scale operations and beneficiation initiatives in multiple countries, especially the DRC.
Infrastructure-Led Model
China’s engagement has often emphasized infrastructure development — railways, processing facilities, and logistics — tied to resource access.
This contrasts with U.S. emphasis on financial and regulatory frameworks.
Global Mineral Supply Chain Influence
While China still dominates many downstream processing capacities (e.g., rare earths refining), African nations are increasingly looking to balance their partnerships between Beijing, Washington, and other investors for greater autonomy.
Africa’s Position Amid Competition
African governments used the platform to emphasize sovereign decision-making — seeking partnerships that deliver real value, skills transfer, local processing, jobs, and infrastructure.
Looking for partnerships with growing trade and economic blocs like the BRICS could just be Africa’s mineral-rich regions’ panacea in as far as fairness and mutual beneficiation is concerned.
What is unfolding today is less visible than the colonial-era scramble, yet its implications may prove just as profound.
At the heart of this renewed race is global strategic competition. China, the United States, Europe, and other actors are seeking secure access to critical minerals and energy supplies.
It is neo-colonialism targeting natural resources resources with intrusions into carefully selected resource-rich regions of the African continent.
This recent resource rush puts Africa’s sovereignty at risk as these targeted states are unfairly dealt with bargaining for their own resources.
Africa should be let to freely decide whom to deal with for mutual benefits.
Apart from the exploitative western powers, Africa has alternatives at it’s disposal such as the BRICS which is one of the fastest growing global economic blocs.
Supply chain security has become a defining concern of modern industrial policy, placing Africa squarely within global power calculations.
No actor has reshaped Africa’s economic landscape more dramatically than China.
Over the past two decades, Beijing has evolved into the continent’s largest trading partner and a dominant investor in infrastructure and extractive industries.
Railways, roads, smelters, ports, and industrial zones financed by Chinese capital now form part of Africa’s physical and economic architecture.
China’s engagement model often combines long-term financing with resource-backed arrangements.
Infrastructure-for-resources agreements under initiatives like the Belt and Road have enabled African states to access funding at a scale rarely matched by Western partners.
For many governments facing infrastructure deficits, this financing filled a critical gap.
Yet the model has generated debate. Critics point to rising debt burdens, limited domestic value addition, and environmental concerns.
The core question persists: does resource extraction financed by foreign capital catalyse industrial transformation, or does it entrench dependency?
Western nations, meanwhile, are recalibrating. The urgency of diversifying mineral supply chains — particularly away from concentrated sources — has triggered renewed diplomatic and commercial engagement with Africa.
Washington and Brussels increasingly frame Africa not just as a development partner but as a strategic economic ally.
Unlike earlier Western investment cycles, the current approach is heavily influenced by regulatory, governance, and environmental standards.
While these conditions may strengthen safeguards, they also introduce complexity and slower deal-making — a contrast frequently noted by African policymakers.
Despite shifting actors, certain patterns remain stubbornly consistent.
Most African economies continue exporting raw materials while importing high-value manufactured goods.
This structure echoes long-standing extractive specialisation that limits industrial diversification and employment growth.
Infrastructure investment — though essential — often reinforces this dynamic.
Railways and ports designed primarily to move minerals to export terminals can deepen extraction pathways without guaranteeing broader industrial ecosystems.
Connectivity alone does not equal transformation.
Still, Africa’s position today is not identical to its past.
Governments are increasingly aware of the risks of resource dependence.
Across the continent, policymakers are experimenting with export restrictions, revised mining laws, and local beneficiation requirements aimed at retaining greater value domestically.
Discover more: https://brnw.ch/21wZLPH
#AfricaExpertise
#InvestedInYourStory
#MiningIndaba2026
The effectiveness of these strategies hinges on institutional capacity.
Regulation, enforcement, technical expertise, and governance transparency remain decisive variables.
Resource nationalism without strong institutions risks creating uncertainty rather than sustainable gains.
Country experiences illustrate both promise and peril.
In Zambia, copper continues to anchor economic fortunes. Once dominated by Western firms, the sector has seen expanding Chinese participation across mining and processing.
Copper’s importance to global electrification ensures Zambia’s enduring strategic relevance.
However, environmental risks have sharpened scrutiny.
Incidents such as the tailings dam failure involving operations linked to Sino-Metals Leach Zambia exposed vulnerabilities in oversight, environmental management, and community protection.
Such episodes underscore how ecological damage can erode development gains.
In the Democratic Republic of Congo (DRC), the stakes are even higher.
Home to some of the world’s richest cobalt and copper deposits, the country sits at the epicentre of the global energy transition.
Mineral wealth has attracted vast foreign investment, particularly from Chinese firms.
Companies including China Molybdenum have secured major positions in extraction and processing chains. While infrastructure development has accompanied investment, value capture largely remains external.
Governance challenges continue to complicate efforts to translate resource wealth into broad-based prosperity.
Angola presents a different trajectory. Long defined by oil dependency, Angola is cautiously diversifying into diamonds and other minerals.
Engagements involving De Beers and the state-owned ENDIAMA reflect attempts to balance foreign partnership with state participation.
Strategic infrastructure such as the Lobito Corridor highlights how geopolitics and logistics intertwine. Competing investment frameworks reveal Africa’s growing centrality in global economic reconfiguration.
In Nigeria, hydrocarbons still dominate. Oil revenues underpin fiscal stability yet expose the economy to volatility, governance pressures, and environmental strain.
Recent interest in lithium processing and green hydrogen signals tentative movement toward diversification.
Across these varied contexts, several themes converge.
First, value chain capture remains limited. Industrial upgrading tied to resource sectors — refining, manufacturing, technology integration — is still underdeveloped.
Without these linkages, extraction alone rarely drives structural transformation.
Second, governance remains the decisive factor.
Transparent contracts, regulatory enforcement, and revenue management determine whether resource wealth benefits broad populations or narrow elites.
Third, environmental and social safeguards are no longer peripheral concerns.
Pollution, displacement, and community discontent carry economic and political costs that directly shape development outcomes.
Fourth, geopolitical competition creates leverage but not automatic advantage.
Africa’s bargaining power increases when multiple actors compete — yet outcomes depend on negotiation capacity and policy coherence.
The long-term question is not whether foreign investment will flow; it will.
The critical issue is whether Africa can convert this attention into durable industrial growth.
Success requires moving beyond extraction toward integrated value creation.
Local processing industries, skills development, technology transfer, and infrastructure aligned with domestic production must become central policy priorities.
Equally vital is institutional strengthening.
Without robust governance frameworks, even well-designed strategies risk dilution through inefficiency, corruption, or regulatory weakness.
Africa’s resource wealth offers extraordinary potential.
The global energy transition could provide a historic opening for industrialisation, manufacturing growth, and technological advancement. But potential does not guarantee outcome.
The modern scramble is ultimately a test of agency.
If African states shape investment on their own developmental terms, the continent may emerge as a value-adding industrial force.
If not, history may record another era of extraction dressed in modern economics.
The stakes could scarcely be higher.